What is the Next-Generation Drug Conjugates Oncology Market scope and definition?
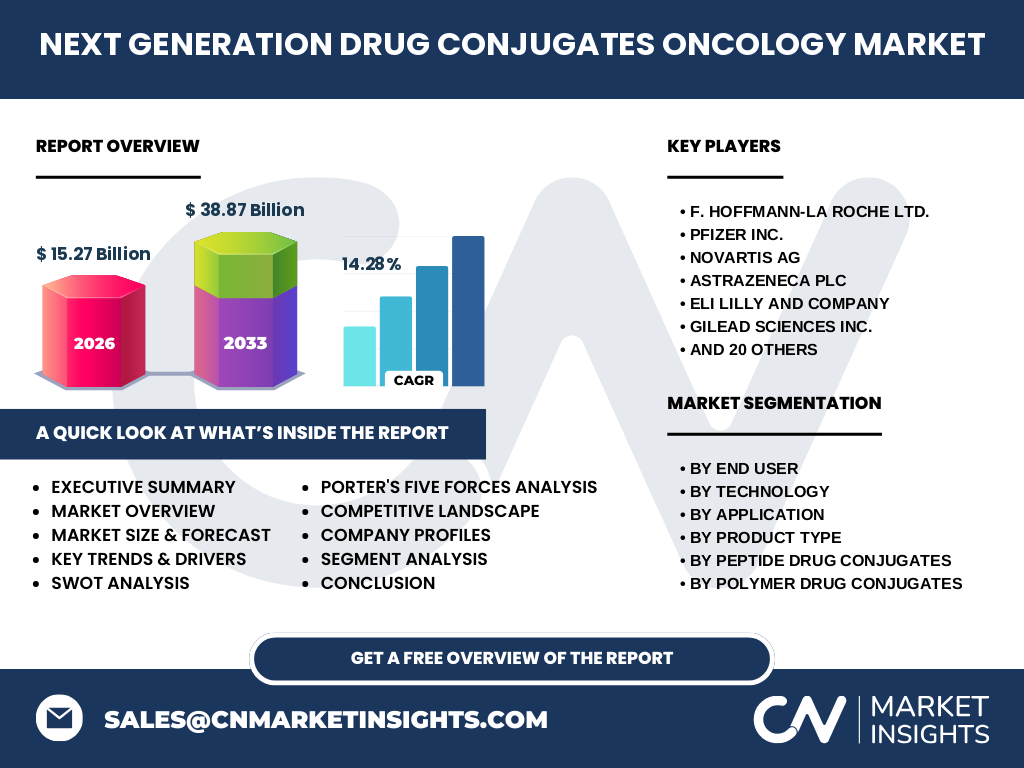
Our analysis indicates that the Next-Generation Drug Conjugates Oncology Market reached 15.27 Billion in 2026, defining a transformative paradigm in precision oncology. This sector encompasses advanced therapeutics engineered to maximize cytotoxic delivery while sparing healthy tissue, driven by breakthroughs from innovators like F. Hoffmann-La Roche Ltd. and AstraZeneca PLC navigating strict FDA and EMA regulatory pathways.
Key market drivers, restraints, challenges, and opportunities shaping Next-Generation Drug Conjugates Oncology Market
The market is propelled by rising oncology pipelines and precision medicine demands, though constrained by complex cold-chain logistics and high manufacturing costs. Opportunities abound for CDMOs like Lonza Group AG and Piramal Pharma Solutions to optimize payload synthesis, mitigating supply chain bottlenecks for raw cytotoxins through strategic facility expansions near major biopharma hubs.
Emerging trends and growth patterns in Next-Generation Drug Conjugates Oncology Market
Industry trends highlight a decisive shift toward site-specific conjugation and dual-payload architectures. Companies such as Mersana Therapeutics and Sutro Biopharma are pioneering homogeneous drug-antibody ratios, significantly improving therapeutic windows and pharmacokinetic profiles compared to legacy random conjugation techniques.
COVID-19 impact analysis — how the pandemic affected Next-Generation Drug Conjugates Oncology Market and the recovery trajectory
While clinical trial recruitments faced initial disruptions during pandemic lockdowns, the recovery trajectory has accelerated due to heightened investor focus on targeted oncology. Regulatory flexibility by bodies like the US FDA streamlined expedited trial designs, enabling rapid capital infusion into clinical-stage biotechs.
Competitive landscape — major players, market concentration, and strategic dynamics
The competitive landscape features intense consolidation through licensing agreements and strategic acquisitions. Industry giants like Pfizer Inc. and Daiichi Sankyo Company Limited dominate via proprietary linker platforms, forcing emerging players like Byondis B.V. and Adcendo ApS to differentiate through highly specialized tumor-targeting mechanisms.
Executive summary of the Next-Generation Drug Conjugates Oncology Market
Our research projects the Next-Generation Drug Conjugates Oncology Market to surge to 38.87 Billion by 2033, expanding at a robust CAGR of 14.28%. This exceptional growth is anchored by accelerating clinical validations in antibody-drug and peptide drug conjugates across major oncology indications.
Market forecast — projected growth from 2027 to 2033
Driven by robust clinical pipelines and increasing commercial approvals, the market baseline valuation of 15.27 Billion in 2026 will scale dramatically to 38.87 Billion by 2033. This trajectory underscores a sustained 14.28% CAGR, fueled by heightened venture capital and licensing deals.
Segmentation analysis of the Next-Generation Drug Conjugates Oncology Market
Market segmentation spans end users (Hospitals, Cancer Treatment Centers, Research Institutes, Specialty Clinics), technologies (Cleavable and Non-Cleavable Linkers, Site-Specific and Random Conjugation), applications (Breast, Lung, Hematological, Colorectal, and Ovarian Cancers), and diverse product types including Antibody-Drug, Peptide, Small Molecule, and Polymer Drug Conjugates.
Regional market analysis and geographic distribution
North America retains the dominant revenue share, supported by advanced healthcare infrastructure and heavy R&D investments by leaders like Eli Lilly and Company and Gilead Sciences Inc. Meanwhile, Asia-Pacific emerges as the fastest-growing region, powered by clinical expansions in China and Japan through firms like Hansoh Pharmaceutical.
In-depth regional review for strategic planning
North America benefits from mature reimbursement frameworks and proximity to major clinical trial sites, while Europe enforces rigorous pharmacovigilance under the European Medicines Agency. In Asia-Pacific, strategic ports in South Korea and Singapore facilitate efficient regional distribution for bioconjugate raw materials.
Company profiles and strategic positioning
Leading entities leverage specialized technological moats: Novartis AG and AbbVie Inc. focus on broad oncology portfolios, whereas specialized innovators like Ajinomoto Bio-Pharma Services Inc. and Alloy Therapeutics Inc. provide essential proprietary expression and conjugation platforms to the broader ecosystem.
Porter's Five Forces analysis of the industry
Competitive rivalry is high, propelled by continuous patent filings for novel linkers. Supplier power remains moderate due to specialized cytotoxic raw material requirements, while threat of substitution is mitigated by the unmatched target specificity of modern antibody and peptide conjugates.
SWOT analysis of Next-Generation Drug Conjugates Oncology Market
Strengths lie in high tumor-targeting precision and expanding clinical pipelines. Weaknesses involve complex manufacturing protocols and cold-chain dependencies. Opportunities center on dual-payload innovations by firms like Adagene Inc., against the threat of stringent regulatory hurdles and patent expirations.
Value chain analysis from raw materials to end-users
The value chain initiates with raw chemical synthesis of payloads and monoclonal antibodies, progressing through specialized bioconjugation facilities managed by CDMOs like Lotte Biologics Co Ltd., and culminating in administration at specialized cancer treatment centers and hospitals worldwide.
Investment insights and high-potential areas
Investors should target early-stage biotechs specializing in site-specific conjugation and tumor-targeting peptide drug conjugates. Companies such as Sichuan Kelun-Biotech and Mersana Therapeutics offer compelling growth potential as targeted oncology adoption accelerates globally.
Conclusion and key takeaways for stakeholders
The Next-Generation Drug Conjugates Oncology Market represents a high-conviction investment sector poised to reach 38.87 Billion by 2033. Success relies on navigating complex biomanufacturing scale-up, partnering with established CDMOs, and leveraging advanced cleavable linker technologies.
Research methodology for baseline estimates
Our analytical rigor combines exhaustive triangulation of trade registry data, primary stakeholder interviews with key opinion leaders across FUJIFILM Corporation and Piramal Pharma, and secondary macroeconomic indicators to project accurate market valuations through rigorous quantitative modeling.
Scope of the report and coverage parameters
This report covers global market dynamics for the Next-Generation Drug Conjugates Oncology Market from 2026 to 2033, evaluating four core product categories, five major application segments, and comprehensive regional breakdowns, excluding non-oncology therapeutic applications of bioconjugates.
Recent developments, partnerships, and strategic moves
Recent market dynamism is highlighted by aggressive co-development partnerships and facility expansions. Innovators such as Byondis B.V. and Alloy Therapeutics Inc. have announced pivotal licensing agreements to advance proprietary site-specific conjugation pipelines through late-stage clinical trials.